Reduced income tax
Preferential rate for industrial users, compared with the 35% general rate.
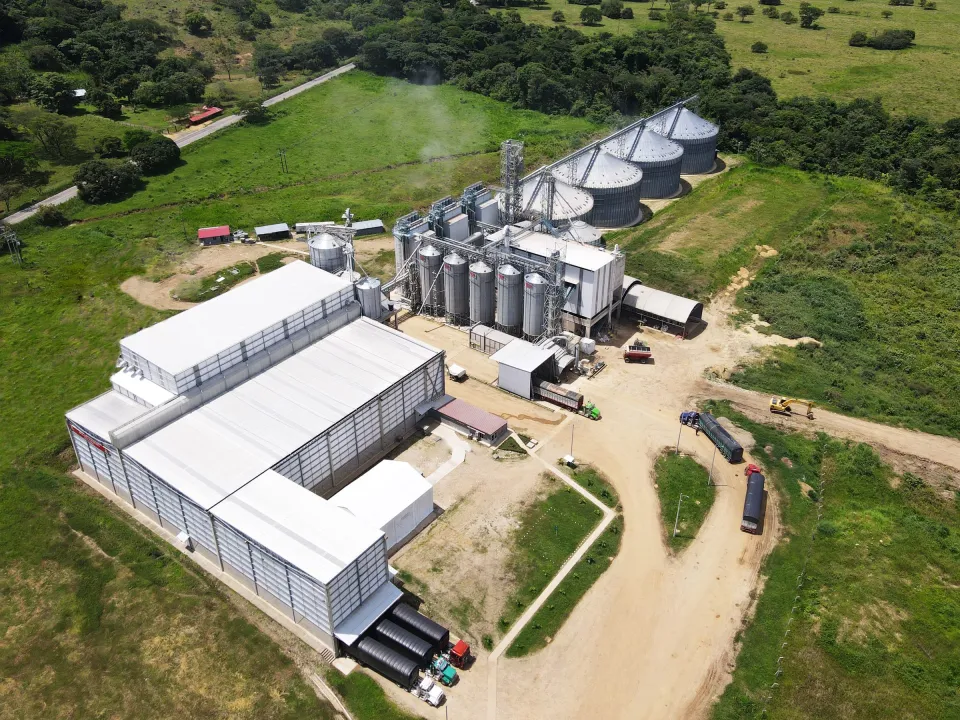
Lower costs, better cash flow and a special foreign trade regime.
Preferential rate for industrial users, compared with the 35% general rate.
Exemption on raw materials, inputs and goods bought in Colombia for operations in the zone.
Foreign goods pay no duties or VAT while they remain in the free trade zone.
Paid only when the product enters the Colombian market.
Benefits apply to qualified users under Colombia's current free trade zone regime (Law 1004 of 2005, Decree 2147 of 2016 and Law 2277 of 2022). The 20% income tax rate is subject to an internationalization plan and legal conditions. Contact our team to assess your case.
| Item | General regime | Free trade zone |
|---|---|---|
| Income tax | 35% | 20% for industrial users (with internationalization plan) |
| Import duties | Paid on import | Suspended while goods remain in the zone |
| VAT on imports | 19% on import | Not triggered while goods remain in the zone |
Benefits apply to qualified users under Colombia's current free trade zone regime (Law 1004 of 2005, Decree 2147 of 2016 and Law 2277 of 2022). The 20% income tax rate is subject to an internationalization plan and legal conditions. Contact our team to assess your case.